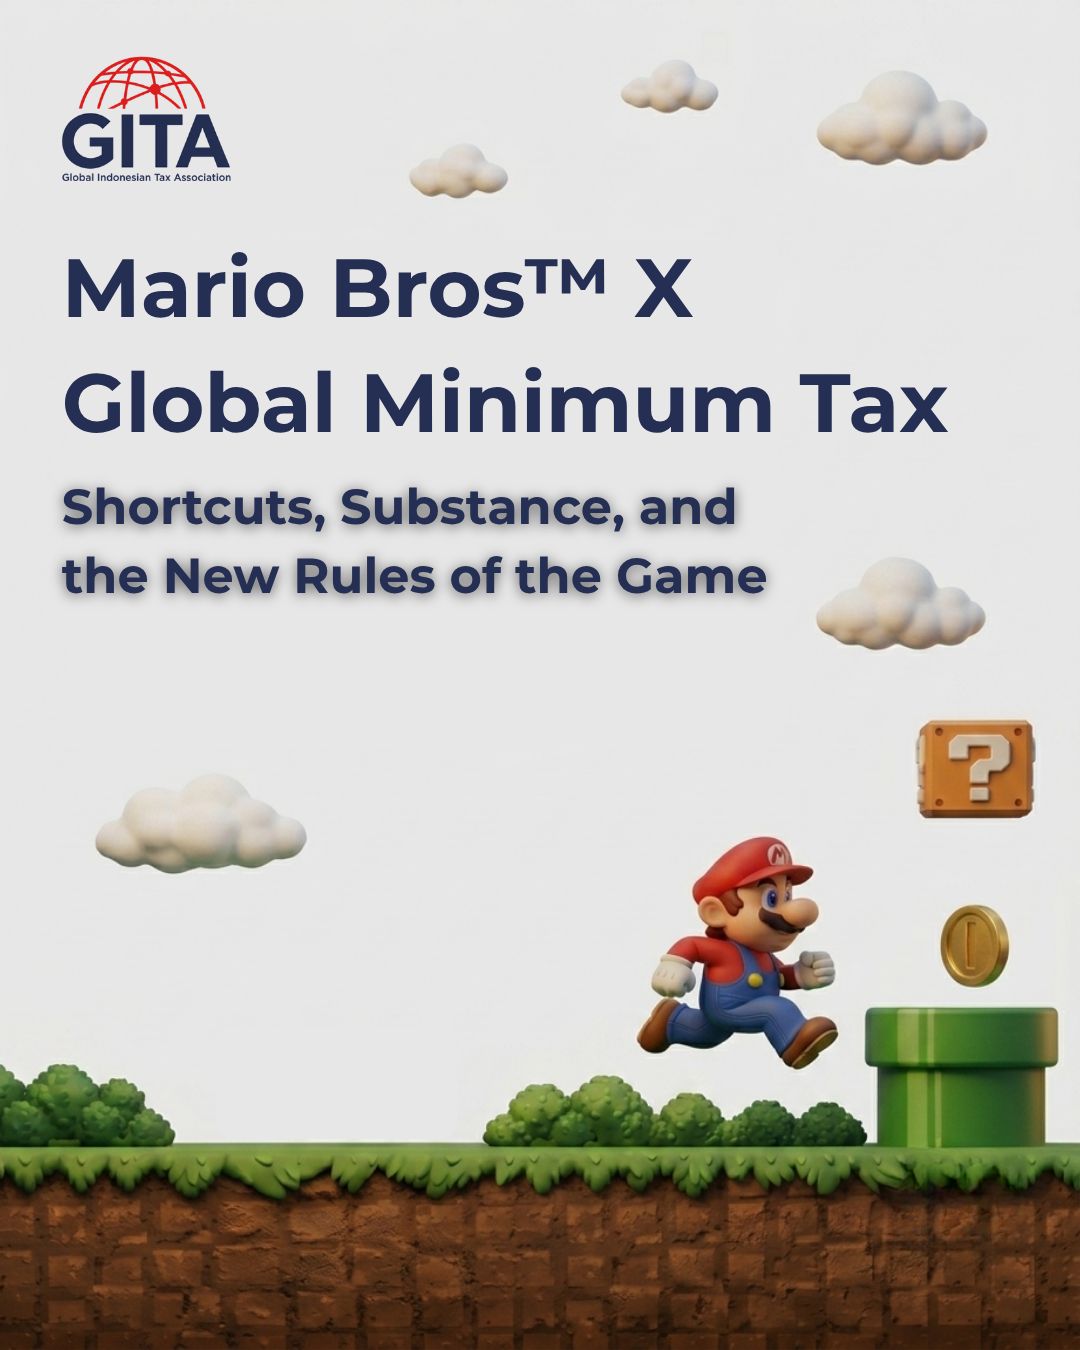
Mario Bros™ has warp pipes. Global tax has cross-border routes. And Pillar Two changes the outcome.
For many years, international tax planning often focused on finding the most efficient route through the global system. Much like a player using a shortcut in a game, multinational groups could structure operations across jurisdictions in ways that produced lower tax outcomes. The policy concern, however, begins when the shortcut becomes more important than the real business activity behind it.
This is where the OECD/G20 Global Minimum Tax framework changes the conversation. Pillar Two does not redraw the map of international business, and it does not prevent multinational groups from operating across borders. Different tax systems still exist, and companies may still use global structures. But the framework introduces a new result: when profits in a jurisdiction are taxed below the 15% minimum threshold, a top-up tax may apply. In simple terms, the route may still exist, but the reward attached to that route may no longer be the same.
That is why the real impact of Pillar Two is not about banning cross-border activity. It is about changing how the game is scored. A low-tax jurisdiction may still be part of a multinational structure, but its advantage is reduced if the effective tax rate falls below the minimum level. The map stays the same. The payoff changes.
This also explains why the discussion is increasingly moving from shortcuts to substance. In a game, what matters is not only reaching the next level, but what the player actually earns along the way. In international tax, the equivalent is real economic substance: people, assets, functions, risks, and genuine business activity. These are becoming more important in determining whether a global tax outcome is sustainable in the new environment.
The broader message is clear. Pillar Two is not trying to eliminate international business structures, nor is it designed to prohibit companies from operating in multiple jurisdictions. Instead, it places a floor under tax outcomes and reduces the benefit of arrangements that rely too heavily on low-tax routes without enough underlying substance. The system is shifting away from access to low-tax results and toward closer alignment with real value creation.
So the takeaway is simple: the game itself is not being cancelled, but the scoring system has changed. Companies may still move across jurisdictions, and cross-border routes may still exist, but substance now matters more than shortcuts. In the new global tax landscape, that may be the most important rule of all.